Impact of Leadership on Company
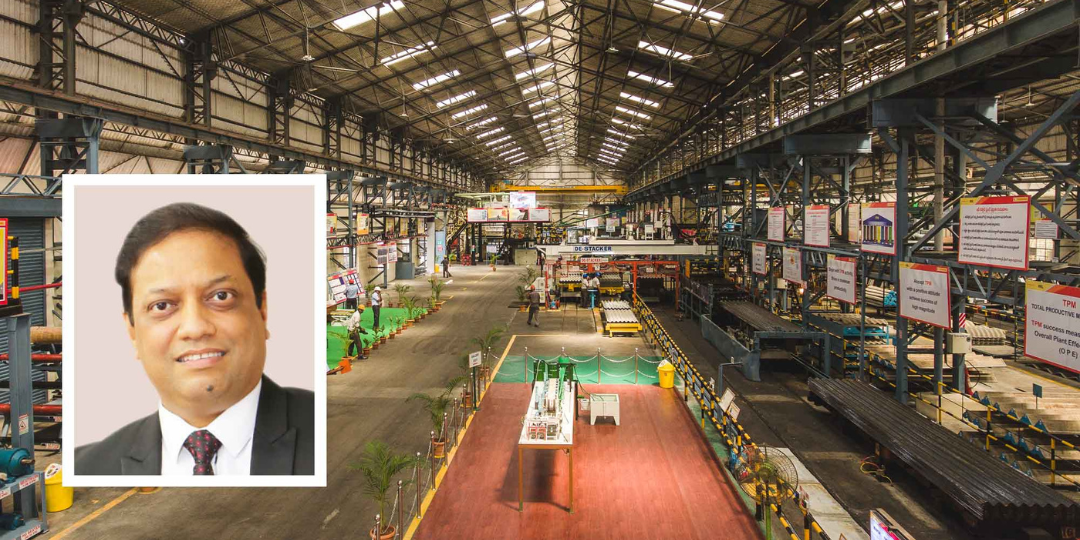
Care PMS was tracking this company from 2015 and had not seen encouraging growth numbers until 2017. The business was always of interest, so we kept watching its performance. In early 2018 an upward trend caught our attention and we began coverage to identify the developments. The notable changes in the business were highly attributable to leadership.
Key facts
Impact on business
| Impact on business | 2013–2016 | 2017–2021 |
|---|---|---|
| Revenue, average growth | 1.77% | 24.59% |
| EBITDA, average growth | –4.60% | 28.96% |
| PAT, average growth | –13.20% | 34.73% |
| EBITDA margin | 9.09% (2016) | 13.34% (9M FY21) |
| Net debt | ₹158 Cr (2016) | ₹150 Cr (9M FY21) |
| RoCE | 11.88% | 15%+ |
| Fibre cement, share of sales | 85–90% | 30% |
The company
- HIL Ltd, flagship of the CK Birla Group, has led asbestos fibre-cement roofing with ~20% market share for over five decades.
- Over 3,950 employees, 20 manufacturing facilities and a ~6,500-strong dealer network.
- Products span fibre-cement sheets, AAC blocks, boards and panels, and pipes and fittings (polymer solutions).
- Owner of consumer super-brands Birla Aerocon and Charminar, with a 70-year building-materials legacy; its in-house R&D centre holds 22 patents across 7 countries.
Turning point, appointment of Mr. Dhirup Roy Chaudhary in 2017
- Engineering graduate of the Birla Institute of Technology and post-graduate of IIM Ahmedabad, with 29 years of business leadership.
- Spent 14 years at ABB, becoming its youngest Business Head.
- Joined Crompton Greaves India as its youngest General Manager, heading Power Transformers, and turned the plant around within months.
- At Bagri Group, Malaysia, grew the company to 6x equity in 7 years as Global Head and President.
- Named “The Most Promising Business Leader of Asia 2018 & 2019” by The Economic Times.
Initiatives of the new leadership
- Cost rationalisation lifted EBITDA margins from 10% in FY17 to 15% in FY19.
- Higher dealer engagement and IPL sponsorship, with MS Dhoni as brand ambassador, drove market-share gains.
- In-house R&D developed the non-asbestos sheet “Charminar Fortune” · hedging asbestos-ban risk and opening the 40% institutional segment.
- The pipes division, entered in 2013, reached ~₹40 Cr revenue by 2017, targeting ₹400 Cr in four to five years and crossing ₹200 Cr in 2021.
- Pricing discipline in FY20 delivered an 18% EBIT margin versus 8% for the next-best player.
A game-changing acquisition, Parador Holdings GmbH, Germany
- Parador is a vertically integrated flooring supplier, resilient, laminate and engineered wood flooring, plus wall and ceiling panels.
- Six Sigma adoption and product innovation lifted EBITDA margins from 7–8% to 12%+ within 18 months.
- Parador renews 50% of its product portfolio every three years.
- It grew through COVID by shifting from a three-layer distribution model to DIY and e-commerce.
- Capacity utilisation of 70% is targeted to exceed 90%, with EBITDA margins expected above 15% within two years.
The growth journey has just begun
- Fibre-cement sheets should perform well near term on a strong monsoon and rising farm income.
- Charminar Fortune is expected to drive 8–10% segment growth over the next two to three years.
- Polymer and Building Solutions should each cross ₹1,000 Cr by FY25, with Polymer margins near 15%.
- Parador is projected to cross ₹2,000 Cr revenue in 18–24 months at ~15% margins.
- A planned entry into adhesives supports the FY25 target of US$1 billion in revenue.
The Care PMS edge, identifying the opportunity in early 2018
- We tracked the company from 2015; an upward trend in early 2018 prompted deeper coverage.
- We met management to understand their ten-year vision of multi-fold growth through launches, branding and acquisitions.
- We invested in 2018; since then revenue has grown ~100%, EPS ~115% and the market price ~80%.
- We believe the company can multiply its earnings over the next decade, backed by strong leadership.
Disclaimer. This report is for the authorised recipient’s personal information and does not constitute investment advice. It is based on public-domain information believed to be reliable, but no representation is made as to its accuracy or completeness. Care PMS is not responsible for any loss arising from inadvertent errors; recipients should rely on their own investigations. Care PMS, through proprietary and client funds, has an interest in the Company.
Begin your Care PMS journey.
Invest directly with a SEBI registered portfolio manager, as a resident or a non-resident investor. Contact us at connect@carepms.com and our team will guide you through every step.
- 01
Consultation
A conversation with our team about your objectives, investment horizon and risk appetite, and the approach best suited to them.
- 02
Documentation
A PMS bank account and demat account are opened in your name. You sign the PMS agreement and grant the Power of Attorney.
- 03
Portfolio activation
Invest fresh funds of ₹50 lakh or more, or introduce an existing portfolio. Statements and reporting follow every month.